Should I sell my Spotify RSUs?
Your Spotify RSUs have built your wealth, but concentration in a stock carries risk. Learn how to protect your gains and shield your family from the 40% US Estate Tax.

Abhighyan Sinha

If you are a Spotify leader or early employee who has seen the company become synonymous with music streaming and get listed, the majority of your net worth is likely in Spotify stocks.
While these RSUs have created wealth, it now creates a risk: your income, your savings, and your financial future are all tied to the performance of a single stock.
This blog talks about how you can protect your Spotify RSU wealth and grow it, and what other Spotify senior folks with significant RSU holdings are doing.
Table of contents
- Risks with Spotify RSUs
- Protect your Spotify RSU wealth
- How to diversify vested Spotify stocks?
- What are the tax implications?
- How to minimize tax burden?
- How Paasa can help
- FAQs
Risks of having a large part of your net worth tied to Spotify stocks
For many Spotify employees, their compensation structure creates a situation where a large part of their wealth ends up being locked in employer stocks.
Here are the risks of having a large part of your wealth in Spotify stocks:
1. Growth Risk
Markets are unpredictable in the short term and growth at the level of individual stocks remains uncertain over any given period.
Even a fundamentally strong stock like Spotify can grow slower than the broader market and even go through extended periods of slow growth.
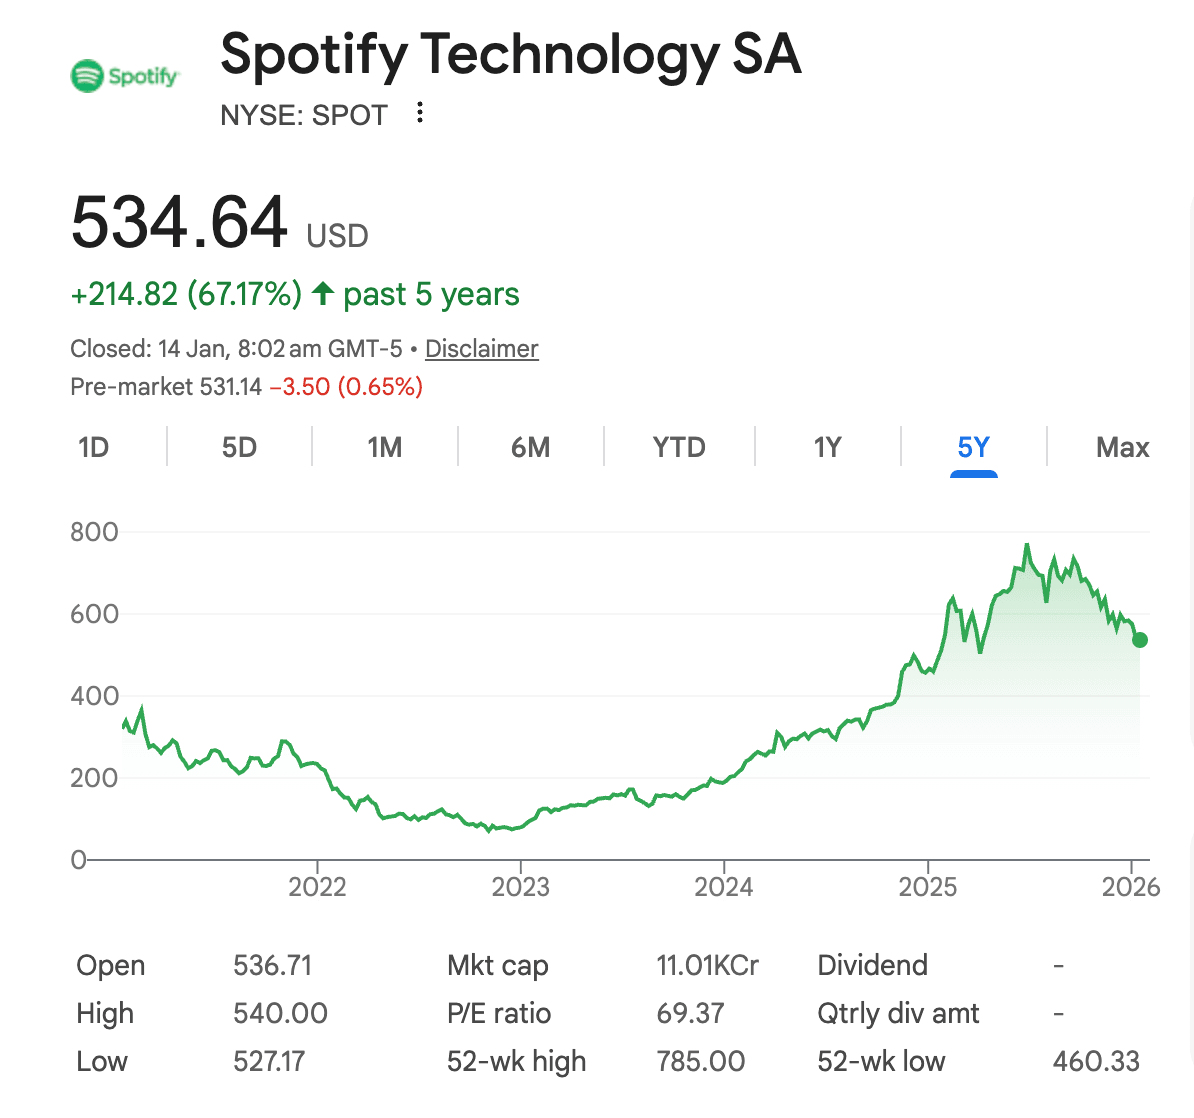
Despite being the market leader, the stock price of Spotify has not caught up to broader market growth for the last few years.
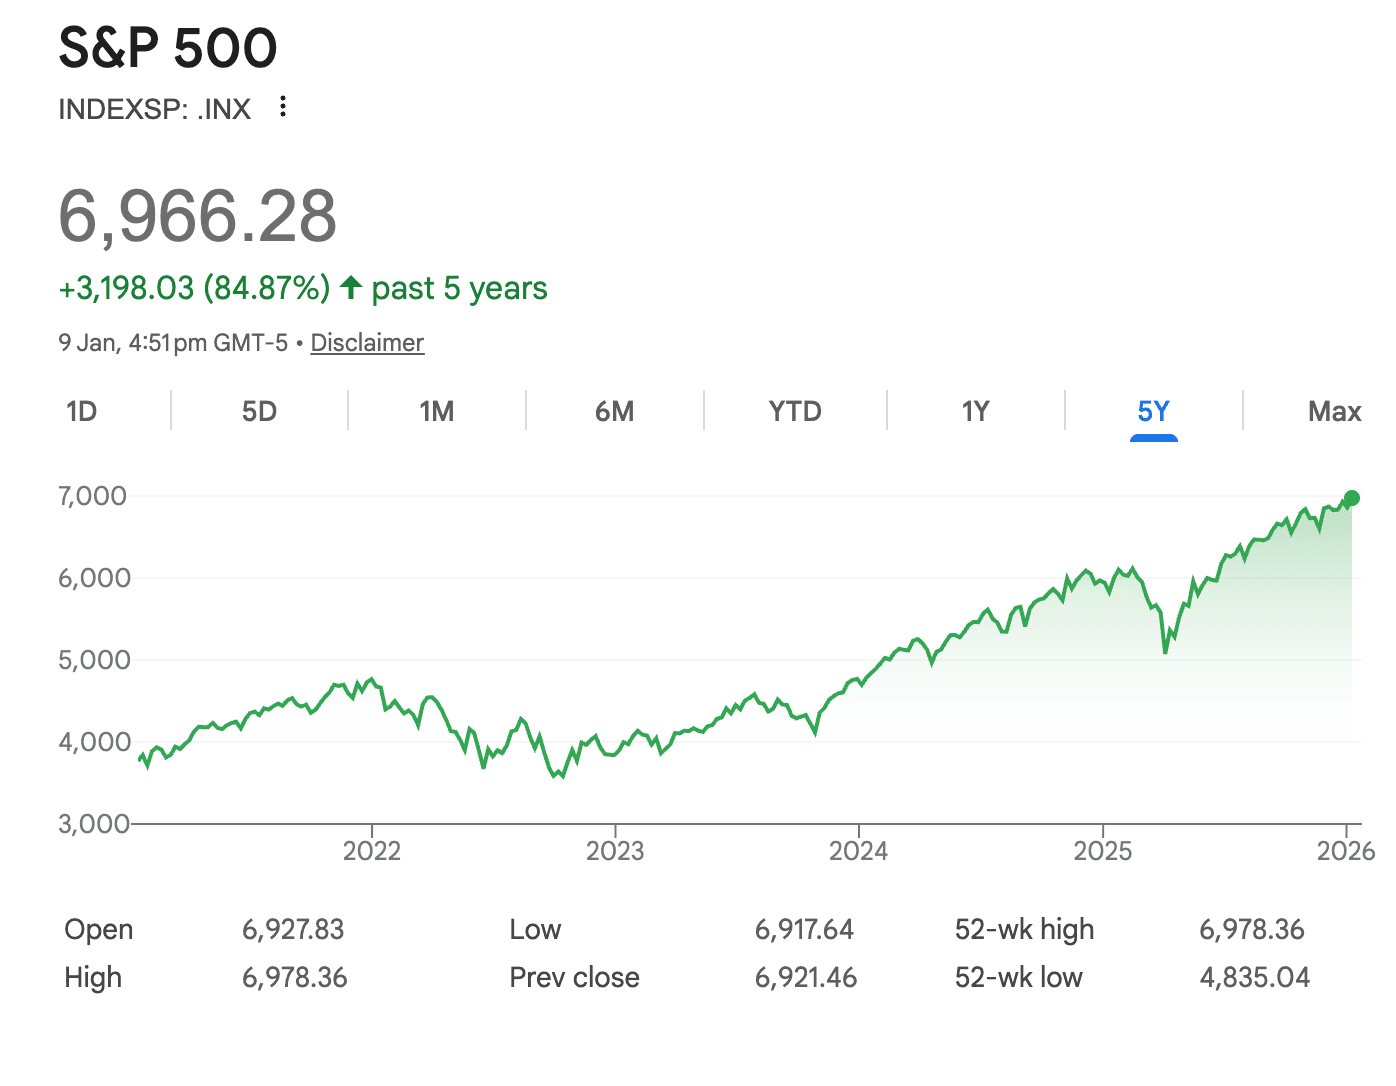
While Spotify grew 67.17% over the past 5 years (as of Jan 2026), the S&P 500 provided returns of 84.87% over the same time period.
Spotify is now a market leader. While this offers stability, mature giants rarely offer the explosive hyper-growth of the broader, diversified mid-cap market.
2. Concentration Risk
Having a large part of your wealth tied up in one stock means that the overall returns of your portfolio will be strongly correlated to that particular company’s performance.
This increases volatility as any growth slowdowns or sectoral changes affecting the company’s stock will also affect your net worth and other financial plans.
For tech professionals with $100k+ in salary compensation, concentration in employer stocks also creates a situation where your income and wealth is tied to the performance of the same company.
3. Wealth erosion due to the 40% US Estate Tax
In the event of your death, all your US assets (like stocks, ETFs, any property in the US, etc) over the $60,000 exemption limit are subject to the US Estate Tax of up to 40%
Since Spotify stocks are US-situs assets, they are subject to the US estate tax.
The US estate tax is an up to 40% tax that needs to be paid on the total value of your US assets upon your death.
US domiciled persons have a $15 million exemption limit, and only assets above this exemption limit are subject to this tax.
However, if you are not US domiciled, the exemption limit for you is only $60,000, and any US-situs asset above this threshold is subject to the US estate tax.
Example
If you have Spotify stocks worth $1.5 million, your family will have to pay a 34.8% tax ($522,000) on this asset upon your death, wiping off more than a third of your RSU wealth instantly. The liability increases if you also have other US assets.
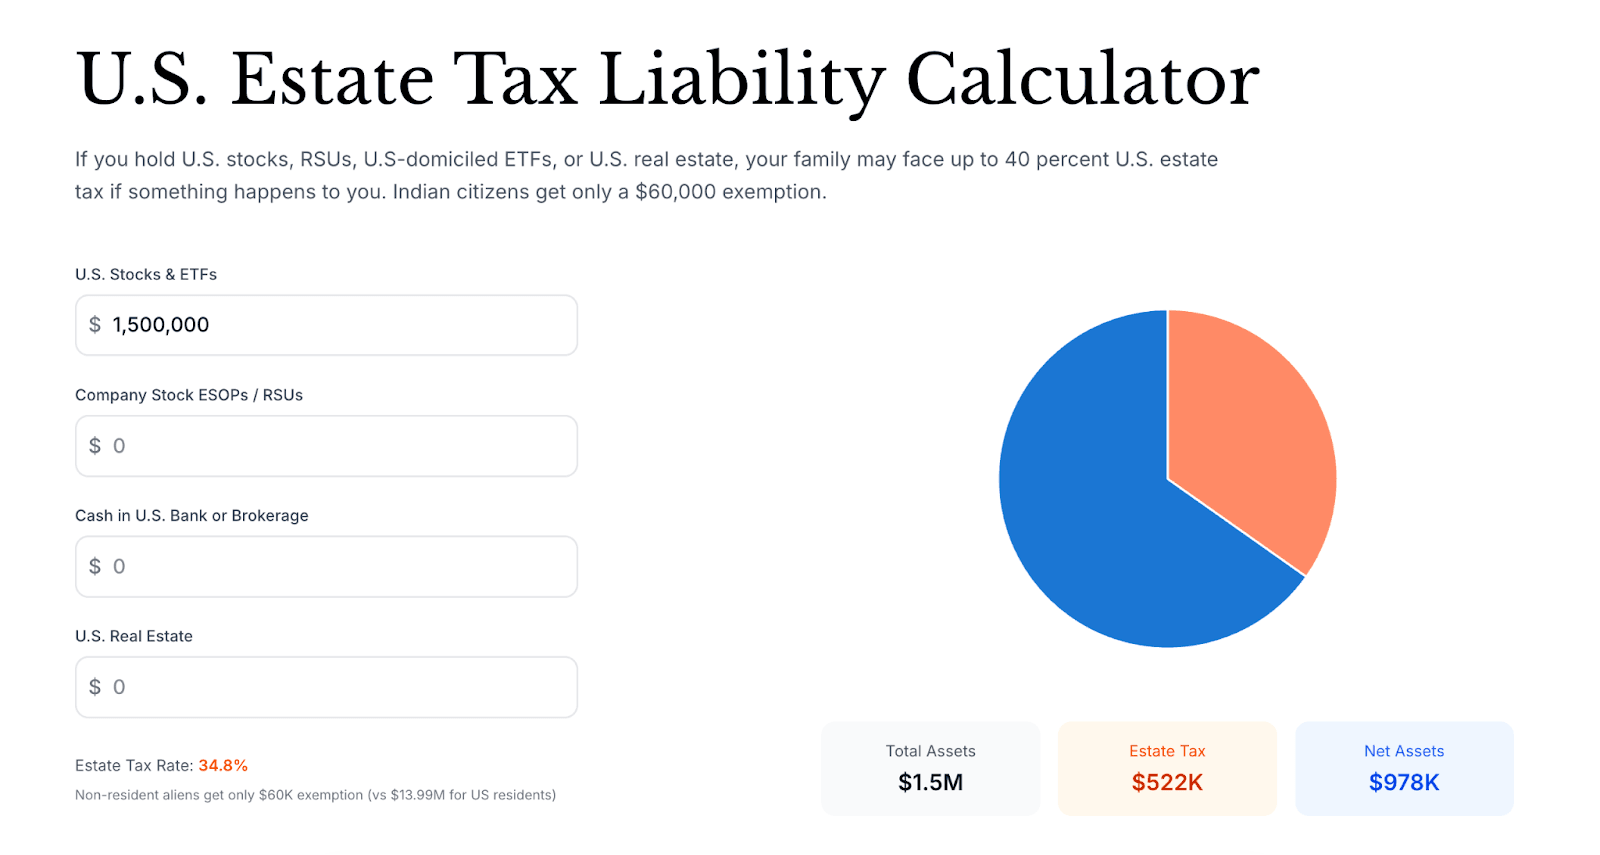
Use our Estate Tax Calculator to find out your exact tax liability.
To learn more about how you can protect your RSUs from the US estate tax, visit our guide on How Indian professionals can protect RSUs from estate tax.
How to protect your Spotify RSU wealth?
Many Spotify employees are mitigating this by selling a portion of their RSUs and diversifying into other stocks and US estate-tax friendly instruments (like UCITS ETFs).
Here’s how diversification protects against the risks we discussed:
1. Spread out the growth risk
Diversification ensures that your portfolio tracks the performance of the broader market rather than relying on a single stock.
Depending on your risk appetite, you can choose funds like S&P 500, target specific sectors like AI or commodities, or go for a combination.
This ensures your wealth follows market-wide growth and isn't limited by the performance of just one company.
2. Eliminate concentration risk
Concentration risk exposes you to volatility, meaning that any abrupt movement in Spotify stock will also have a large effect on your overall portfolio. Diversification reduces this volatility by spreading out the risk over several companies and sectors.
For example, if a large part of your net worth is tied to the Spotify stock, your portfolio will show large swings when the Spotify stock goes up or down significantly.
A diversified portfolio will be less prone to such swings as your risk is spread across several assets, and when some of them are going down, others are going up.
“A portfolio can also hold several stocks and ETFs and still be exposed to the same market risks.
Proper diversification involves investing in assets that behave differently across market environments. “
3. Use UCITS ETFs to avoid the US Estate Tax
Many Indian tech professionals are now using UCITS ETFs to avoid the US Estate Tax while staying invested in the US market.
UCITS ETFs are funds that invest in US markets but are domiciled in Europe, most commonly in Ireland or Luxembourg.
As they are legally situated in the European Union, they are not subject to the US Estate Tax even when they hold US stocks such as Apple, Microsoft, or Google.
Rather than holding the S&P 500, you can hold an equivalent UCITS ETFs and avoid the risk of 40% US Estate Tax.
UCITS ETFs are functionally similar to US ETFs, and only the legal domicile is different.
Use our UCITS Screener to find UCITS compliant investment instruments.
Tax implications of diversifying your Spotify RSUs
When you sell your vested RSUs, you have to pay capital gains tax on the profit you are making.
The rate of capital gains tax is decided by your holding period:
To learn more about the tax liabilities arising from the sale of foreign stocks and ETFs, visit our guide on Capital Gains Tax on Foreign Stocks and ETFs
How to minimize your lifetime tax burden while diversifying your Spotify RSUs
The capital gains tax is unavoidable since you have to sell your vested RSUs to diversify.
But your total tax liability can be optimized by implementing a structured selling plan.
We suggest you sell your RSUs in the following order for minimizing your tax liability:
- Vested RSUs with the highest cost basis. These are units currently trading at a loss or closest to their original vesting price (where you have little to no taxable gain).
- Vested RSUs that fall under LTCG (long term capital gains), starting with the units where you have made the minimum capital gains.
- Vested RSUs that fall under STCG (short term capital gains), starting with the units where you have made the minimum capital gains.
How to diversify your vested Spotify RSUs with Paasa
At Paasa, we make the process of moving from concentrated RSUs to globally diversified portfolios seamless. Here’s how it works:
Step 1: Transfer RSUs via ACATS
Your RSUs are transferred from your broker (like Morgan Stanley, E*TRADE, Charles Schwab, Fidelity) into your Paasa account through the Automated Customer Account Transfer Service (ACATS). This is the standard industry process used by global brokerages.
Step 2: Strategic liquidation
Once your RSUs are in Paasa, you can liquidate them, either partially or fully, depending on your goals.
Step 3: Reinvestment into UCITS ETFs or direct stocks
You can then reinvest into direct global stocks, UCITS ETFs, commodities, or Paasa’s curated managed strategies. This gives you global diversification, estate tax protection, and better tax efficiency.
All your assets in Paasa are held directly with Interactive Brokers, offering unmatched security and peace of mind.
If you want to discuss this with our team and understand it in detail, you can schedule a call with us or write to us at support@paasa.com.
Why many Spotify employees are moving to Paasa
Spotify employees are moving to Paasa for unmatched access to global markets (like Switzerland, China, Japan, Singapore, and more), and for the safety and stability offered by Interactive Brokers.
Whether you want to buy BYD stocks or invest in UCITS ETFs to avoid the US Estate Tax, Paasa has it all.
Paasa works with Indian HNIs, family offices, and institutional investors, bringing the same global access and compliance depth to professionals managing RSU wealth. It offers one of the widest UCITS ETF portfolios available to Indian investors, enabling diversification across equities, bonds, and thematic exposures in multiple markets.
Disclaimer
This material is provided for general information only and does not constitute investment, tax, or legal advice. Paasa does not guarantee any returns or outcomes from the strategies described. All investments and remittances should be made in accordance with applicable RBI, FEMA, and income-tax regulations. Investors are advised to seek independent professional advice before acting on any information contained herein.
Frequently Asked Questions
How does transferring my Spotify RSUs to Paasa work?
We use the ACATS (Automated Customer Account Transfer Service) system to transfer your vested Spotify shares from your current broker to your Paasa account. The process is digital and typically takes 3 to 5 business days.
Will I have to pay taxes immediately when I move my RSUs to Paasa?
No. Transferring your shares via ACATS is not a taxable event. You only pay capital gains tax when you decide to sell the shares to diversify your portfolio.
How much tax will I pay when I sell my Spotify shares?
It depends on how long you have held the shares. If you sell shares held for more than 24 months, you pay a flat 12.5% Long-Term Capital Gains (LTCG) tax. If you sell shares held for less than 24 months, the profit is added to your income and taxed at your applicable slab rate.
How does Paasa help me reduce the tax impact of selling?
Paasa helps you identify and sell your most tax-efficient shares first. We prioritize selling shares with the highest cost basis (lowest profit) or those that qualify for the lower 12.5% long-term tax rate, helping you keep your immediate tax bill as low as possible.
Why are UCITS ETFs better than just buying US ETFs?
US-domiciled ETFs are considered US assets, meaning they are subject to the same 40% US Estate Tax risk as your Spotify stock. UCITS ETFs are domiciled in places like Ireland, which gives you the same global exposure but legally shields you from US Estate Tax liability.
Does holding Spotify stock expose me to US Estate Tax?
Yes. Spotify is a US-domiciled asset. If you are an Indian resident and pass away while holding more than $60,000 worth of US assets (including Spotify stock), your estate could be subject to a US Estate Tax of up to 40% on the value above that limit. Moving to Ireland-domiciled UCITS ETFs eliminates this risk.
Should I hold my Spotify RSUs for more than 2 years to save tax?
While holding for 24 months qualifies you for the lower 12.5% Long Term Capital Gains tax rate, it exposes you to significant single-stock risk. If Spotify stock drops during that period, your loss in capital could be much larger than the tax you saved.
Should Indian employees sell Spotify RSUs immediately after vesting?
If you are looking to diversify, it is advisable to sell RSUs immediately upon vesting. Since you have already paid income tax on the vesting value, holding the stock is effectively the same as using your own cash to buy Spotify shares at the current market price. Selling immediately allows you to move that capital into a diversified portfolio and eliminates the risk of the stock price dropping after you have already paid tax on the higher value.
Can I transfer Spotify RSUs from Morgan Stanley or Fidelity to another broker?
Yes. Once your RSUs have vested, they are just like any other share you own. You can transfer them to a platform like Paasa using the ACATS (Automated Customer Account Transfer Service) system. This allows you to consolidate your holdings or manage your liquidation strategy more effectively without triggering a taxable sale event during the transfer.

Invest in global markets from India

Discussion
Disclaimer
The information provided in this post is for general informational purposes only. It is not intended as professional advice or to replace consultation with qualified professionals. While we strive to ensure the accuracy and reliability of the information presented, we make no representations or warranties of any kind, express or implied, about the completeness, accuracy, reliability, suitability, or availability with respect to the content contained herein. Any reliance you place on such information is therefore strictly at your own risk. We disclaim any liability for any loss or damage, including, without limitation, indirect or consequential loss or damage, or any loss or damage whatsoever arising from loss of data or profits arising out of, or in connection with, the use of this post. Always seek the advice of professionals or relevant authorities regarding your specific situation or circumstances.